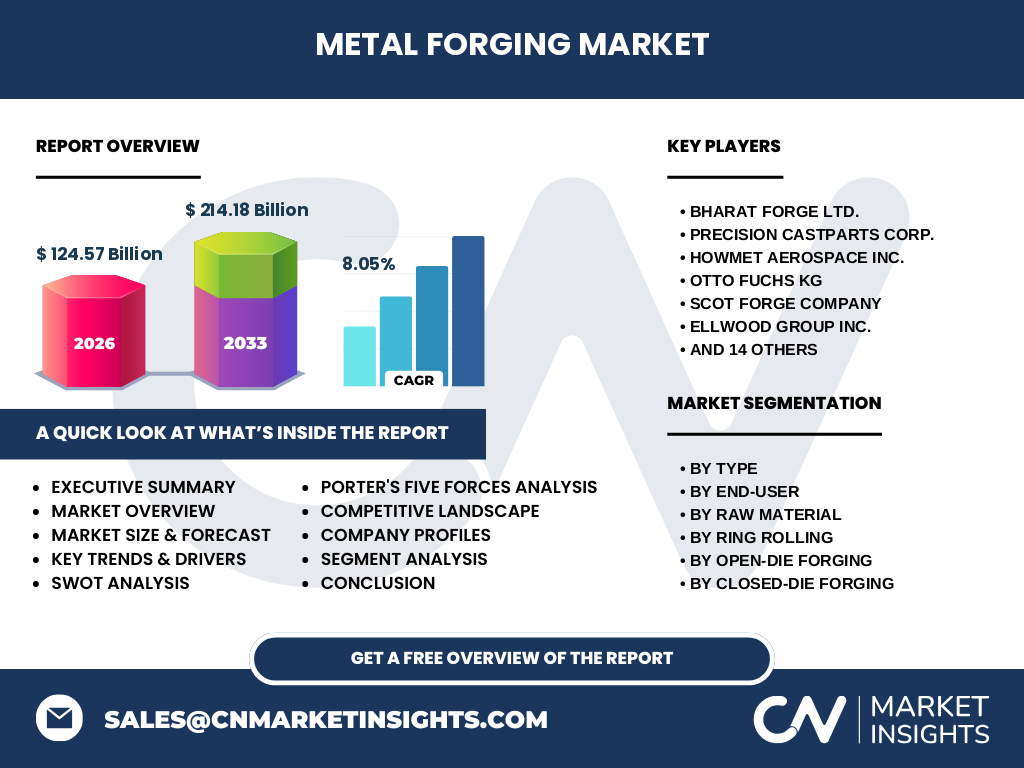
Market overview of the Metal Forging Market
The global Metal Forging Market achieves a valuation of 124.57 Billion in 2026, driven by high-integrity component manufacturing. Our analysis indicates that raw materials like carbon steel and titanium dictate structural integrity across automotive and aerospace tiers. Industry leaders such as Bharat Forge Ltd. and Precision Castparts Corp. anchor this capital-intensive sector.
Key market drivers, restraints, challenges, and opportunities shaping the Metal Forging Market
Demand is accelerated by lightweighting mandates in aerospace, yet restrained by volatile raw material costs for alloy steel. Logistical hurdles near major maritime ports complicate heavy transport. Strategic opportunities emerge in precision closed-die forging for electric vehicle drivetrains, favoring agile operators capable of navigating regulatory oversight by bodies like the FAA.
Emerging trends and growth patterns in the Metal Forging Market
The industry is shifting toward digital twin simulation and advanced induction heating to minimize metallurgical waste. Open-die forging suppliers are adopting radial forging technologies to enhance grain flow in critical defense components, aligning with stringent quality benchmarks enforced by prime contractors like Howmet Aerospace Inc.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain fractures severely impacted Tier-1 suppliers, stalling automotive and commercial aerospace demand. Recovery has been propelled by robust government defense spending and localized reshoring. Based on our research, firms utilizing automated multi-stage forgings rebounded fastest by mitigating labor shortages and securing regional alloy steel supply chains.
Competitive landscape and strategic market concentration
The market features moderate concentration, dominated by multinational heavyweights like Nippon Steel Corporation and Thyssenkrupp AG alongside specialized specialists like Scot Forge Company. Competitive benchmarking reveals that top-tier participants secure long-term supply agreements with OEMs, leveraging proprietary alloy formulations to protect operating margins against low-cost Asian imports.
Executive summary of the Metal Forging Market
Our comprehensive market analysis values the sector at 124.57 Billion in 2026, surging to 214.18 Billion by 2033. Exhibiting a robust CAGR of 8.05%, the industry is fundamentally transformed by lightweighting demands in aerospace, defense, and automotive sectors, rewarding technological innovators with strong pricing power.
Metal Forging Market forecast from 2027 to 2033
Projected to scale from 2027 through 2033 at a steady CAGR of 8.05%, the market will achieve a total valuation of 214.18 Billion by the end of the forecast period. This trajectory is underpinned by massive capital investments in offshore wind energy and next-generation commercial aircraft programs requiring seamless ring rolling.
Segmentation analysis across product types, end-users, and raw materials
The market segments by type into closed-die, open-die, and ring rolling. End-users span automotive, defense, shipbuilding, power, and oil and gas. Raw materials comprise carbon steel, alloy steel, aluminum, stainless steel, and titanium. Precision forgings within closed-die categories capture high margins due to tight dimensional tolerances required by aerospace turbomachinery.
Regional market analysis and geographic distribution
North America and Europe currently dominate consumption, supported by entrenched aerospace and defense clusters. However, Asia-Pacific represents the fastest-growing regional market, driven by rapid industrialization, automotive manufacturing expansion in China and India, and massive shipyard investments utilizing heavy presses from China First Heavy Industries Co. Ltd.
In-depth regional review of manufacturing hubs and logistics
North American production concentrates around the Great Lakes, leveraging proximity to steel mills and vital logistics corridors. European manufacturers face stringent carbon-reduction mandates, forcing companies like Otto Fuchs KG to adopt green hydrogen-powered furnaces. Meanwhile, Asian operators capitalize on lower labor costs and localized raw material access to dominate export markets.
Company profiles and strategic positioning of leading market participants
Industry titans maintain distinct strategic moats. Precision Castparts Corp. and Howmet Aerospace dominate aerospace superalloys. Bharat Forge Ltd. leverages massive commercial automotive scale, while niche players like Scot Forge Company and Ellwood Group Inc. excel in custom, low-volume open-die forgings for heavy machinery and defense applications.
Porter's Five Forces analysis of the metal forging industry
Supplier power remains moderate due to consolidated steel and titanium producers. Buyer power is high among automotive OEMs, pressing for volume discounts. Threat of substitutes is low given the unmatched structural integrity of forged metal over castings. Rivalry is intense, driving continuous R&D in automated multi-stage forging cells.
SWOT analysis of the global sector
Strengths include high product strength-to-weight ratios and entrenched OEM relationships. Weaknesses involve high capital expenditure and energy intensity. Opportunities lie in offshore wind turbine components and EV lightweighting. Threats stem from macroeconomic recessions and volatile nickel and titanium surcharges.
Value chain analysis from raw materials to end-users
The value chain initiates with alloy refiners and scrap recyclers supplying billet and ingot raw materials. Intermediate processors utilize heavy hydraulic presses, drop hammers, and ring rollers. Finished components undergo rigorous non-destructive testing before delivery to tier-one system integrators in aerospace and automotive sectors.
Investment insights and high-potential growth pockets
Investors should target specialized alloy processors supplying the renewable energy sector, particularly offshore wind flange manufacturers. Companies integrating artificial intelligence into closed-die thermal processing exhibit superior EBITDA margins, making them prime candidates for strategic mergers and acquisitions within the forecast window.
Conclusion and key takeaways for strategic decision-makers
The Metal Forging Market presents compelling growth, scaling from 124.57 Billion to 214.18 Billion at an 8.05% CAGR. Success hinges on technological adaptation, sustainability compliance, and strategic alignment with aerospace and defense prime contractors demanding zero-defect metallurgical performance.
Research methodology for baseline estimates and data triangulation
Our analytical framework combines primary stakeholder interviews with forging industry executives, secondary macroeconomic data from trade registries, and customs export statistics. Baseline market size of 124.57 Billion is triangulated using bottom-up manufacturing capacity audits and top-down OEM procurement expenditure modeling.
Scope of the report, coverage parameters, and analytical limitations
This report evaluates the global Metal Forging Market across 2026 base figures and forecasts through 2033. Coverage encompasses all primary material grades, forming techniques, and end-user verticals. Limitations exclude captive forge shops operating exclusively for internal OEM consumption without external market exposure.
Recent developments, corporate partnerships, and strategic expansions
Recent industry momentum highlights aggressive capital expenditure in green manufacturing. Major players like ATI Ladish LLC and Canton Drop Forge Inc. have announced facility expansions optimized for titanium aerospace components, while strategic joint ventures in Asia focus on scaling seamless ring rolling capacity for marine and wind turbine applications.